Magna Concursos

Foram encontradas 47.354 questões.

3456733 Ano: 2024
Disciplina: Inglês (Língua Inglesa)
Banca: NTCS
Orgão: Pref. Mucajaí-RR

De acordo com o texto abaixo, em qual cidade John nasceu?

“Hi! My name is John. I’m twenty five years old. I’m from Vancouver-CA, but I live in Califórnia. I am engineer and finished my graduacion last year in Boston. Jose and Lisa are my parents and they live in Maiami. I have 2 brothers who live in Brazil.”


Provas

Questão presente nas seguintes provas
Text I
Embarking on the ESG journey
Efforts to mitigate the accelerating effects of climate change and address perceived historical social inequities are two powerful issues driving change globally. These movements have enhanced awareness of how all organizations impact, influence, and interact with society and the environment.
They also have spurred organizations to better recognize and manage ESG risks (i.e., risks associated with how organizations operate in respect to their impact on the world around them). This broad risk category includes areas that are dynamic and often driven by factors that can be difficult to measure objectively, such as inclusion, ethical behavior, corporate culture, and embracing sustainability across the organization.
Still, there is growing urgency for organizations to understand and manage ESG risks, particularly as investors and regulators focus on organizations producing high-quality reporting on sustainability efforts. What’s more, that pressure is being reflected increasingly in executive performance as more organizations tie incentive compensation metrics to ESG goals.
Additional risk areas associated with ESG are varied and can include reliance on third-party data, potential reputational damage from faulty reporting, and the real possibility that an organization’s explicit commitments to meet specific sustainability goals could grow into a material weakness.
As ESG reporting becomes increasingly common, it should be treated with the same care as financial reporting. Organizations need to recognize that ESG reporting must be built on a strategically crafted system of internal controls and accurately reflect how an organization’s ESG efforts relate to each other, the organization’s finances, and value creation. […] Seeking out objective assurance on all ESG-related risk management processes from a qualified, independent, and properly resourced internal audit function should be part of any ESG strategy.
Adapted from: https://www.theiia.org/globalassets/documents/ communications/2021/june/white-paper-internal-audits-role-in-esg-reporting.pdf
The text concludes with a
 

Provas

Questão presente nas seguintes provas
Text I
Embarking on the ESG journey
Efforts to mitigate the accelerating effects of climate change and address perceived historical social inequities are two powerful issues driving change globally. These movements have enhanced awareness of how all organizations impact, influence, and interact with society and the environment.
They also have spurred organizations to better recognize and manage ESG risks (i.e., risks associated with how organizations operate in respect to their impact on the world around them). This broad risk category includes areas that are dynamic and often driven by factors that can be difficult to measure objectively, such as inclusion, ethical behavior, corporate culture, and embracing sustainability across the organization.
Still, there is growing urgency for organizations to understand and manage ESG risks, particularly as investors and regulators focus on organizations producing high-quality reporting on sustainability efforts. What’s more, that pressure is being reflected increasingly in executive performance as more organizations tie incentive compensation metrics to ESG goals.
Additional risk areas associated with ESG are varied and can include reliance on third-party data, potential reputational damage from faulty reporting, and the real possibility that an organization’s explicit commitments to meet specific sustainability goals could grow into a material weakness.
As ESG reporting becomes increasingly common, it should be treated with the same care as financial reporting. Organizations need to recognize that ESG reporting must be built on a strategically crafted system of internal controls and accurately reflect how an organization’s ESG efforts relate to each other, the organization’s finances, and value creation. […] Seeking out objective assurance on all ESG-related risk management processes from a qualified, independent, and properly resourced internal audit function should be part of any ESG strategy.
Adapted from: https://www.theiia.org/globalassets/documents/ communications/2021/june/white-paper-internal-audits-role-in-esg-reporting.pdf
The opposite of the adjective in “faulty reporting” (4th paragraph) is
 

Provas

Questão presente nas seguintes provas
Text I
Embarking on the ESG journey
Efforts to mitigate the accelerating effects of climate change and address perceived historical social inequities are two powerful issues driving change globally. These movements have enhanced awareness of how all organizations impact, influence, and interact with society and the environment.
They also have spurred organizations to better recognize and manage ESG risks (i.e., risks associated with how organizations operate in respect to their impact on the world around them). This broad risk category includes areas that are dynamic and often driven by factors that can be difficult to measure objectively, such as inclusion, ethical behavior, corporate culture, and embracing sustainability across the organization.
Still, there is growing urgency for organizations to understand and manage ESG risks, particularly as investors and regulators focus on organizations producing high-quality reporting on sustainability efforts. What’s more, that pressure is being reflected increasingly in executive performance as more organizations tie incentive compensation metrics to ESG goals.
Additional risk areas associated with ESG are varied and can include reliance on third-party data, potential reputational damage from faulty reporting, and the real possibility that an organization’s explicit commitments to meet specific sustainability goals could grow into a material weakness.
As ESG reporting becomes increasingly common, it should be treated with the same care as financial reporting. Organizations need to recognize that ESG reporting must be built on a strategically crafted system of internal controls and accurately reflect how an organization’s ESG efforts relate to each other, the organization’s finances, and value creation. […] Seeking out objective assurance on all ESG-related risk management processes from a qualified, independent, and properly resourced internal audit function should be part of any ESG strategy.
Adapted from: https://www.theiia.org/globalassets/documents/ communications/2021/june/white-paper-internal-audits-role-in-esg-reporting.pdf
When the text informs that the efforts have “spurred organizations” (2nd paragraph), this means that the organizations have been
 

Provas

Questão presente nas seguintes provas
Text I
Embarking on the ESG journey
Efforts to mitigate the accelerating effects of climate change and address perceived historical social inequities are two powerful issues driving change globally. These movements have enhanced awareness of how all organizations impact, influence, and interact with society and the environment.
They also have spurred organizations to better recognize and manage ESG risks (i.e., risks associated with how organizations operate in respect to their impact on the world around them). This broad risk category includes areas that are dynamic and often driven by factors that can be difficult to measure objectively, such as inclusion, ethical behavior, corporate culture, and embracing sustainability across the organization.
Still, there is growing urgency for organizations to understand and manage ESG risks, particularly as investors and regulators focus on organizations producing high-quality reporting on sustainability efforts. What’s more, that pressure is being reflected increasingly in executive performance as more organizations tie incentive compensation metrics to ESG goals.
Additional risk areas associated with ESG are varied and can include reliance on third-party data, potential reputational damage from faulty reporting, and the real possibility that an organization’s explicit commitments to meet specific sustainability goals could grow into a material weakness.
As ESG reporting becomes increasingly common, it should be treated with the same care as financial reporting. Organizations need to recognize that ESG reporting must be built on a strategically crafted system of internal controls and accurately reflect how an organization’s ESG efforts relate to each other, the organization’s finances, and value creation. […] Seeking out objective assurance on all ESG-related risk management processes from a qualified, independent, and properly resourced internal audit function should be part of any ESG strategy.
Adapted from: https://www.theiia.org/globalassets/documents/ communications/2021/june/white-paper-internal-audits-role-in-esg-reporting.pdf
The word “address” in “address perceived historical social inequities” (1st paragraph) is a(n)
 

Provas

Questão presente nas seguintes provas
Text I
Embarking on the ESG journey
Efforts to mitigate the accelerating effects of climate change and address perceived historical social inequities are two powerful issues driving change globally. These movements have enhanced awareness of how all organizations impact, influence, and interact with society and the environment.
They also have spurred organizations to better recognize and manage ESG risks (i.e., risks associated with how organizations operate in respect to their impact on the world around them). This broad risk category includes areas that are dynamic and often driven by factors that can be difficult to measure objectively, such as inclusion, ethical behavior, corporate culture, and embracing sustainability across the organization.
Still, there is growing urgency for organizations to understand and manage ESG risks, particularly as investors and regulators focus on organizations producing high-quality reporting on sustainability efforts. What’s more, that pressure is being reflected increasingly in executive performance as more organizations tie incentive compensation metrics to ESG goals.
Additional risk areas associated with ESG are varied and can include reliance on third-party data, potential reputational damage from faulty reporting, and the real possibility that an organization’s explicit commitments to meet specific sustainability goals could grow into a material weakness.
As ESG reporting becomes increasingly common, it should be treated with the same care as financial reporting. Organizations need to recognize that ESG reporting must be built on a strategically crafted system of internal controls and accurately reflect how an organization’s ESG efforts relate to each other, the organization’s finances, and value creation. […] Seeking out objective assurance on all ESG-related risk management processes from a qualified, independent, and properly resourced internal audit function should be part of any ESG strategy.
Adapted from: https://www.theiia.org/globalassets/documents/ communications/2021/june/white-paper-internal-audits-role-in-esg-reporting.pdf
The phrasal verb that may replace “mitigate” in “Efforts to mitigate” (1st paragraph), without significant change in meaning, is
 

Provas

Questão presente nas seguintes provas
Text I
Embarking on the ESG journey
Efforts to mitigate the accelerating effects of climate change and address perceived historical social inequities are two powerful issues driving change globally. These movements have enhanced awareness of how all organizations impact, influence, and interact with society and the environment.
They also have spurred organizations to better recognize and manage ESG risks (i.e., risks associated with how organizations operate in respect to their impact on the world around them). This broad risk category includes areas that are dynamic and often driven by factors that can be difficult to measure objectively, such as inclusion, ethical behavior, corporate culture, and embracing sustainability across the organization.
Still, there is growing urgency for organizations to understand and manage ESG risks, particularly as investors and regulators focus on organizations producing high-quality reporting on sustainability efforts. What’s more, that pressure is being reflected increasingly in executive performance as more organizations tie incentive compensation metrics to ESG goals.
Additional risk areas associated with ESG are varied and can include reliance on third-party data, potential reputational damage from faulty reporting, and the real possibility that an organization’s explicit commitments to meet specific sustainability goals could grow into a material weakness.
As ESG reporting becomes increasingly common, it should be treated with the same care as financial reporting. Organizations need to recognize that ESG reporting must be built on a strategically crafted system of internal controls and accurately reflect how an organization’s ESG efforts relate to each other, the organization’s finances, and value creation. […] Seeking out objective assurance on all ESG-related risk management processes from a qualified, independent, and properly resourced internal audit function should be part of any ESG strategy.
Adapted from: https://www.theiia.org/globalassets/documents/ communications/2021/june/white-paper-internal-audits-role-in-esg-reporting.pdf
Based on Text I, mark the statements below as true (T) or false (F).

( ) Social inequalities have prevented endeavors toward change in ESG.
( ) The standards for ESG reporting should be less rigid than those for financial reporting.
( ) Proper internal auditing requires precise ESG reporting.

The statements are, respectively,
 

Provas
Questão presente nas seguintes provas
3455055 Ano: 2024
Disciplina: Inglês (Língua Inglesa)
Banca: FUVEST
Orgão: USP
Provas:

Enunciado 3987935-1

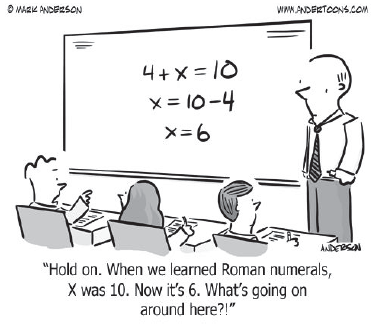
Disponível em https://andertoons.com/math/cartoon/7359/.

Contribui para o efeito de comicidade do cartum a


Provas

Questão presente nas seguintes provas
3455039 Ano: 2024
Disciplina: Inglês (Língua Inglesa)
Banca: FUVEST
Orgão: USP
Provas:

Os versos a seguir pertencem à canção Fall on Me, da banda norte-americana R.E.M., lançada em 1986.

“There's a problem, feathers, iron

Bargain buildings, weights and pulleys

Feathers hit the ground before the weight can leave the air”

Bill Berry, Peter Buck, Mike Mills e Michael Stipe.

A qual episódio (real ou hipotético) da história da física o trecho da música faz alusão?


Provas

Questão presente nas seguintes provas
3455021 Ano: 2024
Disciplina: Inglês (Língua Inglesa)
Banca: FUVEST
Orgão: USP
Provas:

TEXTO PARA A QUESTÃO.

“Quick, quick, tell me something awful

Like you are a poet trapped inside the body of a finance guy

Tell me all your secrets, all you'll ever be is

My eternal consolation prize

You see, I was a debutante in another life, but

Now I seem to be scared to go outside

If comfort is a construct, I don't believe in good luck

Now that I know what's what

I hate it here so I will go to secret gardens in my mind

People need a key to get to, the only one is mine

I read about it in a book when I was a precocious child

No mid-sized city hopes and small-town fears

I'm there most of the year 'cause I hate it here

I hate it here

My friends used to play a game where

We would pick a decade

We wished we could live in instead of this

I'd say the 1830s but without all the racists

And getting married off for the highest bid

Everyone would look down 'cause it wasn't fun now

Seems like it was never even fun back then

Nostalgia is a mind's trick

If I'd been there, I'd hate it

It was freezing in the palace”

“I hate it here”, Taylor Swift, do álbum The Tortured Poets Department, 2024 (Adaptado).

No texto, a percepção de “conforto como construto” indica que o eu lírico vê o conforto como


Provas

Questão presente nas seguintes provas